Can an Equipment Loan Calculator Help You Compare Different Loan Options?
Buying equipment is an important step for many businesses. Whether you run a small business, manage a construction company, or want to expand your services, the right equipment can help you work faster and serve more customers. However, buying new equipment can be expensive. Many business owners choose equipment financing to spread the cost over time instead of paying the full amount at once.
Before choosing a loan, it is important to understand how much you will pay each month and how much the loan will cost in total. Different lenders may offer different interest rates, repayment periods, fees, and loan conditions. Comparing these details can help you make a better financial decision.
An equipment loan calculator can make this process easier. It allows you to estimate loan payments and compare different financing options before making a commitment. With the right information, you can understand which option may fit your business needs and budget.
What Is an Equipment Loan Calculator?
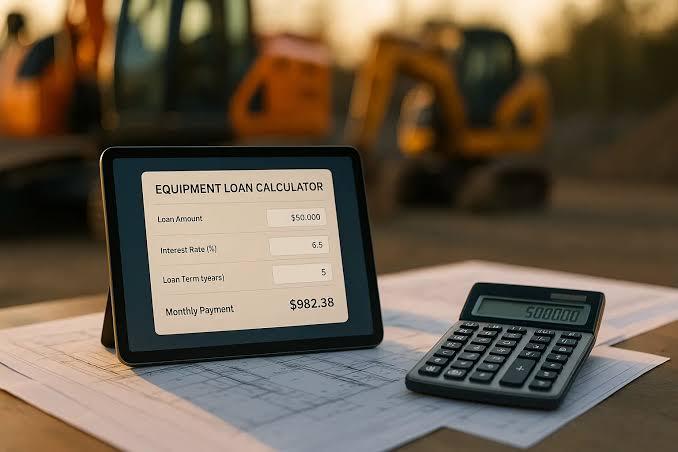
An equipment loan calculator is a financial tool that helps business owners estimate the cost of borrowing money to purchase equipment. You can enter details such as the loan amount, interest rate, and repayment period to calculate your estimated monthly payment.
For example, suppose you want to buy equipment worth $30,000. You plan to borrow the money and repay it over several years. By entering the loan details into the calculator, you can get an idea of how much you may need to pay each month.
This information helps you plan your business budget before applying for financing. Instead of guessing your monthly expenses, you can use estimated figures to understand your possible financial commitment.
Smart Business Credit can help business owners understand their financing needs and explore ways to make informed decisions about business credit.
How Can an Equipment Loan Calculator Help You Compare Different Loan Options?
An equipment loan calculator is useful because it allows you to compare financing options using the same basic information. You can change the interest rate, loan term, or amount borrowed to see how these changes may affect your payments.
For example, one lender may offer a lower interest rate but require a shorter repayment period. Another lender may offer a higher rate with a longer repayment period. The monthly payment for each option may be different, and the total amount paid over time may also vary.
By calculating each option separately, you can better understand the differences. This makes it easier to decide whether lower monthly payments, lower total borrowing costs, or a shorter repayment period is more important for your business.
The calculator does not choose a loan for you. Instead, it provides useful estimates that support your decision.
Compare Monthly Payments From Different Loans
Monthly payments are one of the first things business owners consider when comparing equipment financing. Your monthly payment affects how much money remains available for other business expenses, including rent, employee wages, supplies, and marketing.
An equipment loan calculator allows you to compare estimated payments for loans with different terms and interest rates.
For example, imagine you need to borrow $20,000 to purchase business equipment. You receive two possible financing offers. One has a shorter repayment period, while the other allows you to repay the loan over a longer period.
The shorter loan may require higher monthly payments, but you could pay less interest overall. The longer loan may have lower monthly payments, but the total borrowing cost could be higher.
Comparing these estimates helps you decide which payment amount your business can manage comfortably.
Understand How Interest Rates Affect Loan Costs
Interest rates play an important role in the total cost of equipment financing. The interest rate determines how much you pay to borrow money, although the final cost also depends on the repayment term, fees, and loan structure.
Even a small difference in interest rates can affect your payments over time. For this reason, it is helpful to compare offers from different lenders rather than choosing the first option you receive.
An equipment loan calculator lets you enter different interest rates while keeping the loan amount and repayment period the same. This helps you see how the rate affects your estimated monthly payment.
For example, you might compare a loan with a 7% interest rate against one with a 10% interest rate. The calculator can show how the estimated payments differ under the same repayment conditions.
Remember that the rates available to your business may depend on factors such as your credit history, business finances, loan amount, and lender requirements.
Compare Short-Term and Long-Term Financing
The repayment period is another important factor when choosing equipment financing. Some loans must be repaid within a few years, while others allow a longer repayment period.
A short-term loan usually means higher monthly payments because you repay the borrowed amount over less time. However, it may reduce the total interest you pay.
A long-term loan can make monthly payments more affordable by spreading them across more months. This may help businesses that need to protect their cash flow. However, a longer repayment period can increase the total interest cost.
An equipment loan calculator helps you compare these possibilities before making a decision.
For example, you can calculate the estimated payments for a three-year loan and a five-year loan. Compare both monthly payments and total repayment amounts to understand the financial impact of each option.
The best repayment period depends on your income, regular expenses, and how quickly the equipment is expected to generate value for your business.
Calculate the Total Cost of Equipment Financing
A loan with a low monthly payment is not always the least expensive option. To understand the real cost of financing, you should consider the total amount you will repay.
The total cost can include the amount borrowed, interest, and additional charges required by the lender. Some financing agreements may also include origination fees, documentation fees, or other costs.
An equipment loan calculator can help estimate the principal and interest payments. Some calculators also allow you to include additional fees, while others do not.
For a fair comparison, review the complete terms of each loan offer. Check whether the lender requires a down payment and whether any fees must be paid separately.
This approach helps you avoid choosing a loan based only on its monthly payment. It also gives you a clearer understanding of how much the equipment will cost your business over time.
See How Different Loan Amounts Affect Your Budget
Sometimes, business owners do not need to borrow the full price of their equipment. They may have savings available for a down payment or may decide to purchase less expensive equipment.
An equipment loan calculator can help you compare different borrowing amounts. You can enter a higher or lower loan amount and see how the estimated payments change.
For example, if the equipment costs $25,000 and you can pay $5,000 upfront, you may only need to borrow $20,000. A smaller loan amount can reduce your monthly payments and the interest charged on the borrowed money.
However, using savings for a down payment also reduces the cash available for other business needs. You should consider both the benefits of borrowing less and the importance of maintaining enough working capital.
Comparing different loan amounts helps you find a balance between affordable payments and healthy business cash flow.
Can an Equipment Loan Calculator Help Small Businesses?
Yes, an equipment loan calculator can be especially useful for small businesses because they often need to manage limited budgets carefully.
Small business owners may need equipment to increase production, improve service quality, or complete more projects. However, taking on a loan without understanding its cost can create financial pressure.
Using a calculator before applying for financing helps you estimate whether the expected payments fit your budget. You can compare different loan terms and consider how payments may affect your other expenses.
For example, a small business purchasing a new machine can estimate the monthly payment and compare it with the additional income the machine may generate. This can help the owner evaluate whether the purchase is financially reasonable.
The calculator cannot guarantee that a loan will be approved or that the equipment will generate enough income. It is a planning tool that helps you make decisions using estimates rather than guesses.
What Information Do You Need to Use an Equipment Loan Calculator?
To get useful results, you should collect a few basic details before using the calculator.
First, determine the equipment purchase price and how much money you want to borrow. If you plan to make a down payment, subtract that amount from the purchase price to estimate the required loan amount.
Next, check the interest rate offered by the lender. If you are comparing several offers, use the rate provided for each loan rather than assuming that every lender will charge the same rate.
You should also know the repayment period. This may be expressed in months or years, depending on the calculator.
Finally, review any fees, down payment requirements, or special repayment conditions. If the calculator does not include these details, make sure you consider them separately when comparing the results.
The more accurate your information is, the more useful your estimates will be. However, the final payment may still differ from the calculator's result because of lender-specific terms and charges.
Important Factors to Check Before Choosing a Loan
Although an equipment loan calculator makes comparisons easier, monthly payments should not be the only factor in your decision.
Review the interest rate, total repayment amount, loan duration, and any additional fees. You should also check whether the lender requires collateral, a personal guarantee, or a minimum credit score.
Some financing agreements may include early repayment charges or restrictions on how the equipment can be used. Others may have special rules if you miss a payment.
Read the loan agreement carefully before signing it. Make sure you understand the payment schedule and the consequences of late payments.
You should also consider the expected useful life of the equipment. Taking out a loan that lasts longer than the equipment is likely to remain useful may create problems for your business.
Smart Business Credit can be a starting point for business owners who want to better understand their financing needs and prepare for equipment-related borrowing decisions.
Common Mistakes to Avoid When Comparing Loan Options
One common mistake is choosing a loan only because it has the lowest monthly payment. A longer repayment period may make payments smaller while increasing the total interest cost.
Another mistake is ignoring additional fees. Even when two loans have similar interest rates, their total costs may differ because of lender charges and other conditions.
Some business owners also underestimate their regular expenses. Before accepting a loan, consider whether your business can afford the payments during slower sales periods or unexpected financial challenges.
Finally, avoid treating calculator results as a guaranteed loan offer. The figures are estimates based on the information you enter. Your actual loan terms will depend on the lender's assessment and the agreement you receive.
By avoiding these mistakes, you can use the calculator more effectively and compare your options with greater confidence.
Conclusion
An equipment loan calculator can help you compare different loan options by showing how loan amounts, interest rates, and repayment periods affect your estimated payments. It also helps you understand the difference between affordable monthly payments and the total cost of borrowing.
For business owners, this information can make equipment financing easier to plan. You can compare multiple offers, estimate your budget requirements, and identify potential financial risks before accepting a loan.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek